What Buyers Question First in a Service Business

Sep 29 / Ralph Robinson

A profitable owner sits down across from a buyer for the first time and expects to talk about growth. Instead, the buyer asks who handles the biggest client relationships. The owner says, "I do, mostly," and watches the conversation shift in a way that has nothing to do with the P&L.

This happens more often than owners expect because profit is only part of what a buyer is testing. Profit is the headline. The deeper question is whether those earnings can hold up under someone else's ownership. The diligence process is an investigation into whether that headline number will survive contact with someone else's ownership. A business that earned $900,000 last year under a founder who personally ran sales, approved every hire, and fielded the angry-client calls is not the same asset as a business that will earn $900,000 next year under a stranger. Buyers know this. Owners frequently do not, because they have never had to think about their company as something someone else will have to run.
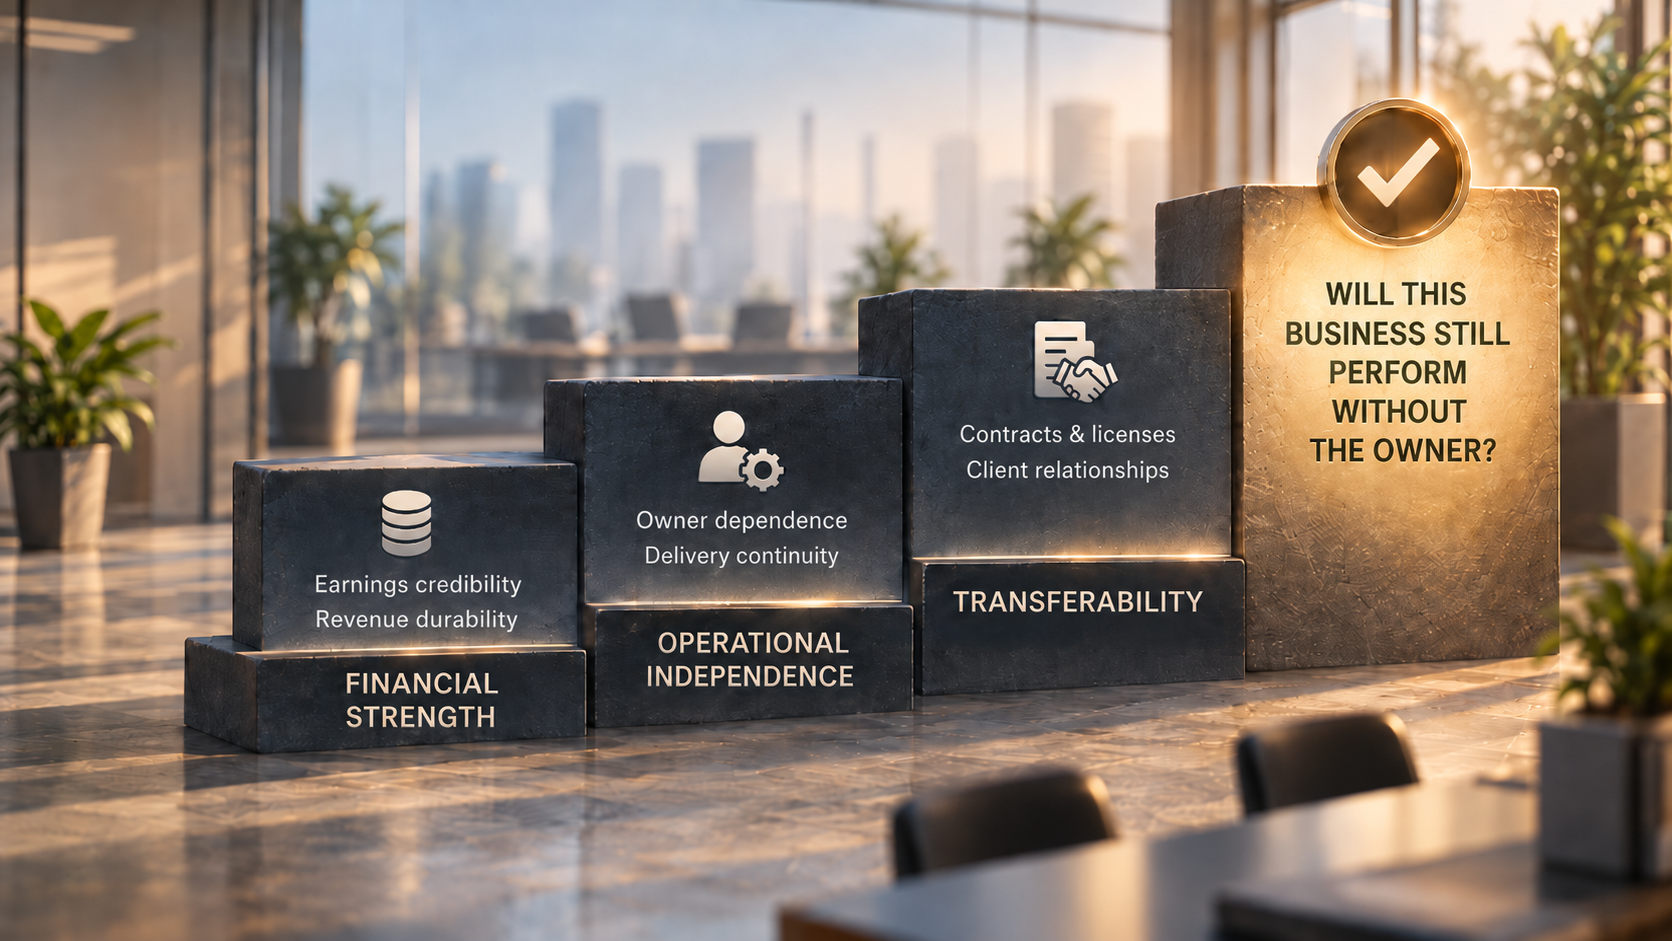
There is no universal script that every buyer follows in the same order. Deal size, financing structure, and industry all shift the sequence. But across acquisition guides, brokerage frameworks, and buyer-seller research, a handful of questions surface again and again near the start of any serious look. Treating them as a rough first-pass sequence, rather than a rigid checklist, gives owners something more useful than reassurance: it gives them a way to find their own weak points before someone else does.

Are the earnings real, and are they yours to keep?

Before a buyer asks about growth, they ask whether the numbers on the page match the money moving through the bank. This is the quality-of-earnings question, and it's more forensic than owners tend to expect. Reported revenue gets checked against deposits. Adjustments to EBITDA get tested for support rather than taken on faith. And then comes the harder version of the same question: does this business generate cash flow independently of the owner, or does the owner's unpaid labor quietly prop up the margin?

If an owner handles most of the sales calls and draws no salary for it, a buyer isn't underwriting the business as it appears on paper; they're underwriting it minus the cost of hiring someone to do what the owner currently does for free. A company that can't support a market-rate general manager's salary while still covering debt service isn't as valuable as its trailing EBITDA suggests, no matter how clean the bookkeeping looks. This is often the first place a profitable-looking business quietly loses ground: not because the earnings were fabricated, but because they were never truly transferable in the first place.

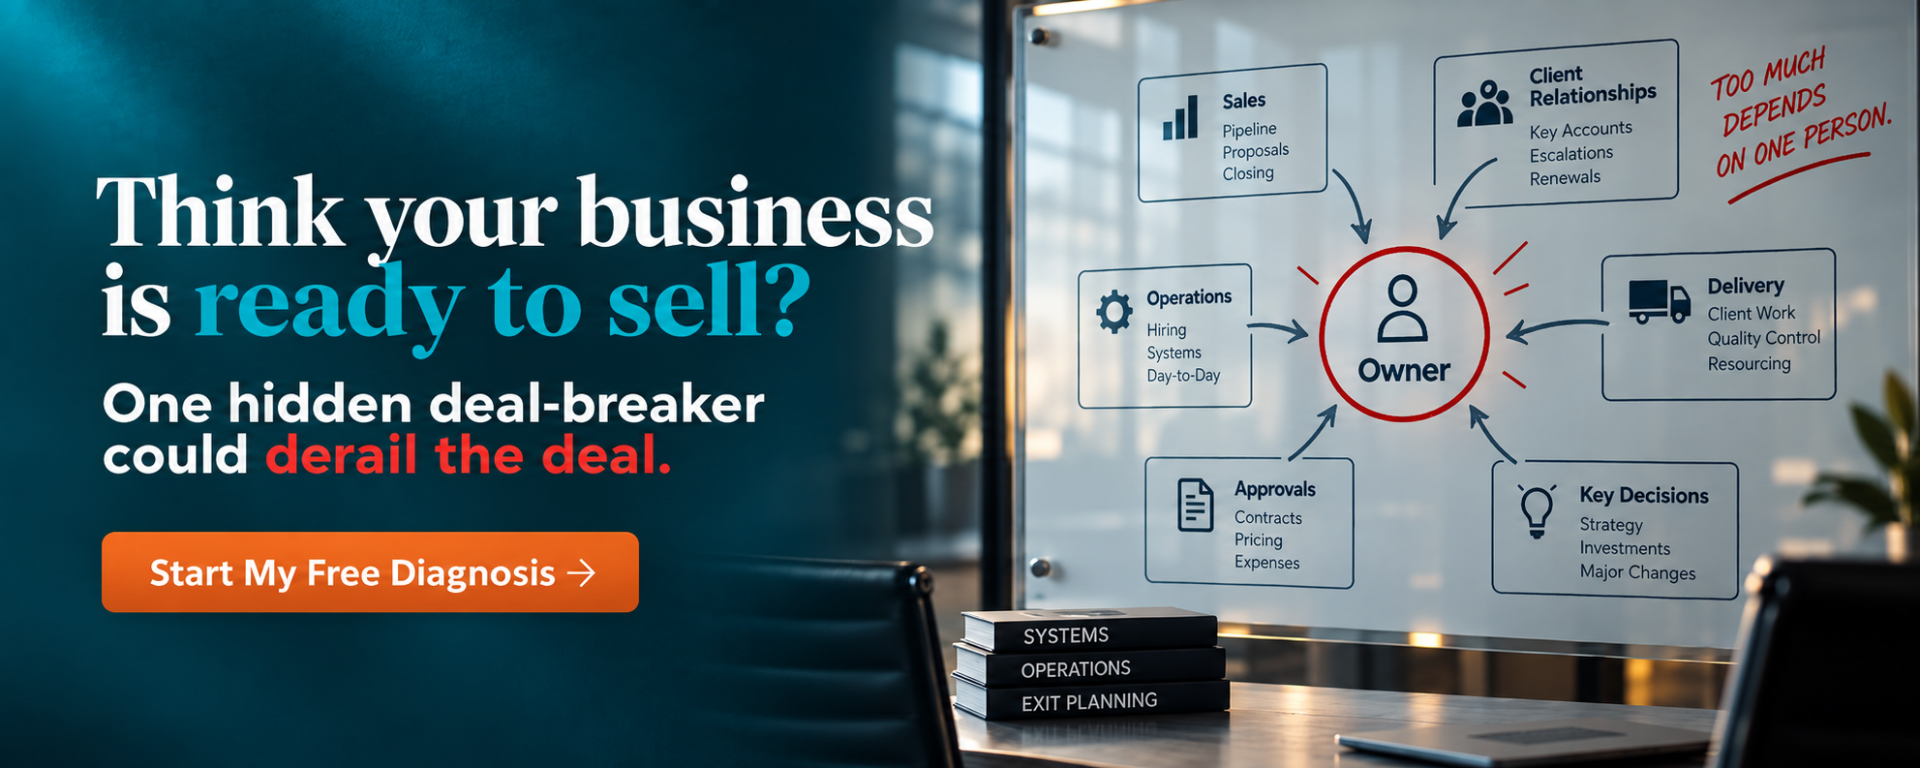
What breaks when the owner leaves?

This is frequently described as the single biggest driver of value in a service business, and it shows up early for a simple reason: it's the fastest way for a buyer to gauge how much risk they're actually buying. The test isn't whether the owner works hard. It's whether the business has a memory that lives outside the owner's head.

Buyers look for documented procedures instead of tribal knowledge, delegated authority instead of an owner who signs off on every invoice, and a management layer (even a thin one) capable of running daily operations without a phone call to the founder. They ask, directly or indirectly, "what would happen if you left tomorrow?" and the answer an owner gives in the moment matters less than the systems that would actually answer for them. An owner who says "my team could handle it" but has never tested that claim is offering an opinion, not evidence.

This is also where client relationships get scrutinized specifically. A founder who personally owns every account relationship is holding value hostage, even if the accounts themselves are stable. The question isn't just whether the clients are loyal. It's whether they're loyal to the company or to the person who might be leaving.

How dependable is the revenue, really?
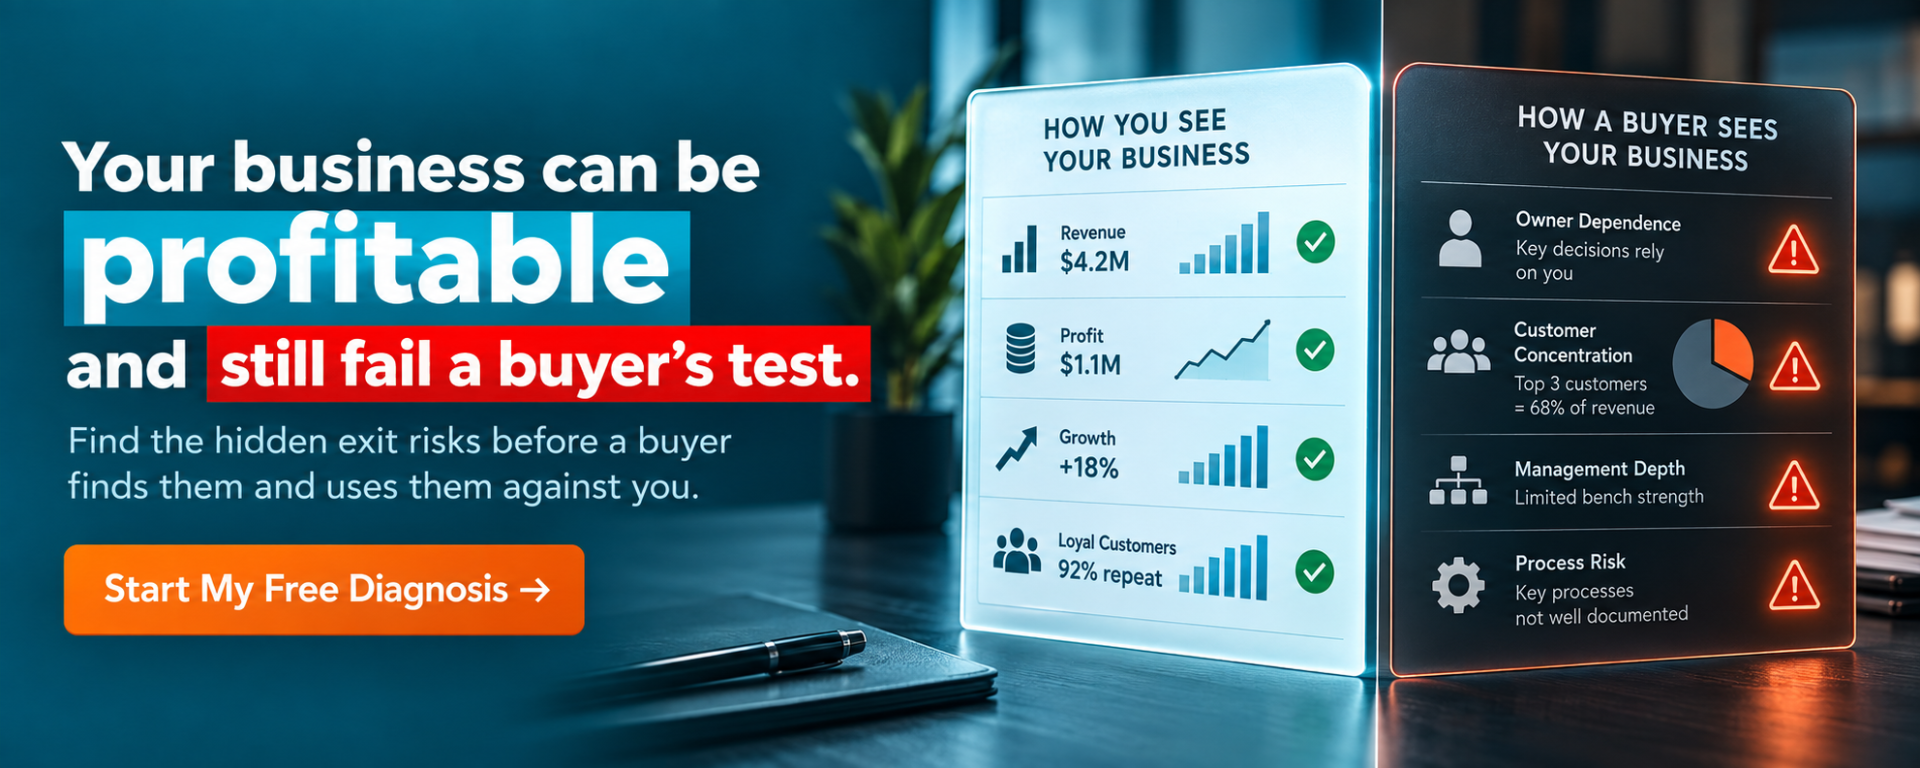
Total revenue is a headline number. Buyers are more interested in its shape: how much repeats without being re-sold, how concentrated it is among a handful of accounts, and what a bad month actually looks like. A buyer will underwrite a business with strong recurring contracts and modest concentration very differently from one with the same revenue spread across one-off projects and a top client that represents a third of the book.

This is also where cohort behavior gets examined: not just this year's client list, but how last year's clients and the year before's clients have behaved over time. Churn, retention, and the split between contract-based and project-based work all feed into the same underlying question: if this business keeps operating exactly as it has, does the revenue keep showing up, or does it require constant new hunting to replace what walks away?

Can the team hold service quality through a change of hands?

Even a business that isn't owner-dependent in the ways described above can still be fragile if the delivery team is thin, undertrained, or churning. Buyers look at turnover, training requirements, and whether quality control lives in a documented process or in one experienced employee's judgment. A field-service company with strong route density and healthy margins can still worry a buyer if the technicians who make those numbers work are unlikely to stay past the transition.

This question tends to matter differently depending on category. In a business where the "product" is a person showing up and doing consistent work (cleaning, HVAC, consulting, agency delivery), the workforce isn't a cost line. It's the delivery mechanism for everything else being evaluated.

Will the contracts and relationships actually transfer?

A business can look financially sound and operationally independent and still carry a structural problem: key agreements that don't survive a change of ownership. Vendor contracts with change-of-control clauses, client agreements requiring consent to assign, licenses tied to a specific individual. These are the kind of details that don't show up in a P&L but can quietly cap what a buyer is willing to pay or how they're willing to structure the deal.

For business-services firms in particular, this question often collapses into one blunt version: do the clients belong to the firm, or to the founder personally? A consulting practice where every account manager introduces themselves as "so-and-so's team" rather than "the firm" is answering that question before anyone asks it out loud.

Does growth look earned, or does it look fragile?
Growth potential matters, but buyers rarely take it at face value. Buyers want to see whether the historical growth trajectory reflects real capacity and systems, or whether it reflects the owner working longer hours and stretching thinner. Projections built on hope rather than data tend to get discounted quickly. Untapped capacity, underused equipment, or a team that could absorb more volume without proportional cost increases are treated as real evidence. A forecast with no operational backing behind it is treated as marketing.

None of this unfolds in identical order every time. A lender-financed buyer may push earnings verification even harder and earlier. A strategic acquirer already familiar with the industry may go straight to customer concentration. A search fund evaluating a founder-led firm may open with owner dependence because that risk alone can kill the deal outright. The emphasis shifts by buyer type, by category, and by whatever red flag surfaces first in the initial materials, which is exactly why treating this as a fixed order would be its own kind of mistake.

What doesn't shift is the underlying logic: buyers aren't buying last year's number. They're buying whatever version of the business survives the transition, and they test that survivability from multiple angles before they ever get to talking price. An owner who has only ever measured the business by its profit has answered a question nobody in diligence is actually asking first.

The more useful exercise isn't guessing which question comes first. It's finding out, honestly, which of these questions your business would currently fail, while there's still time to fix it instead of explain it. A short self-assessment can surface exactly where that exposure sits; take the quiz to see which of these questions your business is least prepared to answer.

Ralph Robinson

Founder, Exit Mastery Blueprint
Ralph Robinson is an experienced business owner and founder of Exit Mastery Blueprint. His perspective is shaped by buyer-side experience evaluating businesses, making offers, and walking away when deals did not hold up under scrutiny. He also brings over 20 years of experience operating owner-led service businesses.
Created with